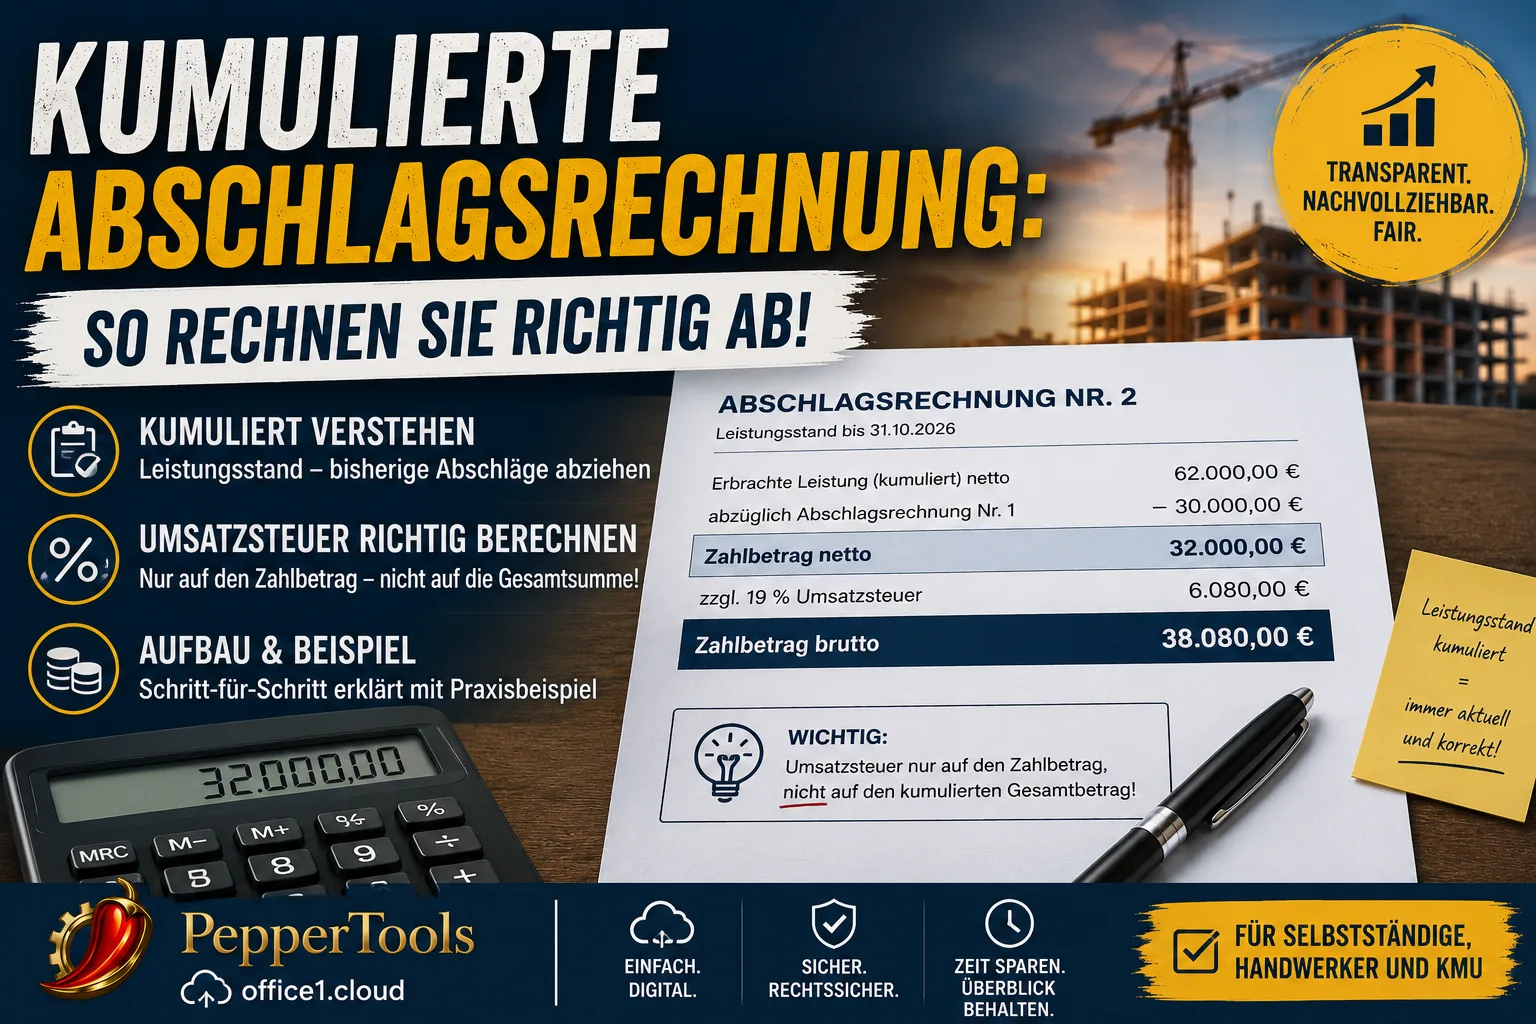
Cumulative means this: every progress invoice shows all the work completed so far and deducts everything you have already billed on this job. What remains is the amount you are asking for this time.
The VAT belongs on that remaining amount only – not on the large figure at the top. If you show VAT on the cumulative total, you owe it to the tax office even though the money never reached you (§ 14c paragraph 1 of the German VAT Act, UStG). That is the one expensive mistake in this type of invoice.
No law prescribes the cumulative format. Neither § 632a of the German Civil Code (BGB) nor § 16 of the German construction contract rules (VOB/B) says how the statement has to look. The client asks for it – usually main contractors and public authorities, because it lets them see at a glance how much of the job is done.
Contents
- Cumulative or single: the difference in one table
- A cumulative progress invoice from top to bottom
- VAT: the mistake that costs 5,700 euros
- Do you have to bill cumulatively?
- Early payment discount: what it applies to
- Retention: deduct yes, save tax no
- What is left for the final invoice
- If you got it wrong
- When your money falls due
Cumulative or single: the difference in one table
Both routes are allowed, and both end with the same money. They differ only in what appears on the page.
| Single progress invoice | Cumulative progress invoice | |
|---|---|---|
| What is at the top? | only the work since the last invoice | all work since the job started |
| Are earlier payments deducted? | no | yes, every one of them |
| What is at the bottom? | the amount for this period | the amount for this period |
| Does the client see the progress? | only if he adds it up himself | yes, in every invoice |
| Where do you correct a revised measurement? | in the final invoice | in the next progress invoice |
That last point is the real reason large clients insist on it. If a measurement is revised downwards or an item is dropped, the correction shows up in the next cumulative invoice on its own. The completed work is recalculated every time. With single progress invoices you carry the error all the way to the final invoice.
For you that has a pleasant consequence: you do not need to cancel a progress invoice you set too high. You enter the correct figure next time, and the difference evens out.
If you want to write invoices with all mandatory details in a few minutes, you can try the invoicing software Easy Invoice free for 10 days.
A cumulative progress invoice from top to bottom
The layout is always the same, whether you do drywall, electrics or plumbing. Example: a job worth 90,000 euros net.
Progress invoice no. 1 – work completed after six weeks: 30,000 euros net.
| Item | Amount |
|---|---|
| Work completed to 15 Sep 2026 (net) | 30,000.00 € |
| less billed so far | 0.00 € |
| Amount due, net | 30,000.00 € |
| plus 19 % VAT | 5,700.00 € |
| Amount due, gross | 35,700.00 € |
Progress invoice no. 2 – work completed now: 62,000 euros net.
| Item | Amount |
|---|---|
| Work completed to 31 Oct 2026 (net) | 62,000.00 € |
| less progress invoice no. 1 (net) | – 30,000.00 € |
| Amount due, net | 32,000.00 € |
| plus 19 % VAT | 6,080.00 € |
| Amount due, gross | 38,080.00 € |
Progress invoice no. 3 – work completed now: 81,000 euros net.
| Item | Amount |
|---|---|
| Work completed to 15 Dec 2026 (net) | 81,000.00 € |
| less progress invoices no. 1 and 2 (net) | – 62,000.00 € |
| Amount due, net | 19,000.00 € |
| plus 19 % VAT | 3,610.00 € |
| Amount due, gross | 22,610.00 € |
Three things stand out:
The top line grows, the bottom one moves up and down. The completed work only goes up (or back down after a correction); the amount due depends on what has been added since the last invoice.
Deduct net from net. You can also deduct gross from gross – but then the VAT of the earlier invoices has to come off as well, otherwise the result is wrong. The net route is less error-prone because the tax appears only once, right at the bottom.
Every one of these invoices needs the standard mandatory details. § 14 paragraph 4 UStG applies here too: full addresses, your tax number or VAT identification number, the date of issue, a sequential invoice number, the type and extent of the work, the net amount, the tax rate and the tax amount. One point is often missing on progress invoices: it must be clear that you are billing for work that is not yet finished. A line such as „Progress invoice no. 2 for job 2026-114, work not yet completed" is enough.
Under a VOB contract you also need a verifiable statement. § 16 paragraph 1 VOB/B requires you to document the work so that the client can assess it „quickly and reliably" – measurements, quantities, unit prices. Without that statement the progress payment does not fall due, no matter how tidy the invoice looks.
VAT: the mistake that costs 5,700 euros
This is where cumulative invoices go wrong.
The reassuring answer first: if you build the invoice as shown above, you do not pay a single cent of VAT twice. The cumulative format is only a different presentation of the same amounts.
Look at progress invoice no. 2 again. The top shows 62,000 euros. The bottom shows 32,000 euros. The VAT belongs on the 32,000 euros, because that is the only amount you are asking for. That is 6,080 euros.
Charge 19 percent on the 62,000 euros instead and you show 11,780 euros of VAT – 5,700 euros too much. The consequence is set out in § 14c paragraph 1 UStG: anyone who shows a higher tax amount in an invoice than he owes still owes the excess. You would owe 5,700 euros of tax that nobody ever transferred to you – the same 5,700 euros you already paid over on progress invoice no. 1.
The background is simpler than it sounds. On progress payments the VAT does not arise with the invoice but when the money arrives. That is what § 13 paragraph 1 no. 1 letter a UStG says: if the payment, or part of it, is received before the work is finished, the tax on that part arises when the money comes in. Every incoming payment is taxed exactly once. Show the tax on the cumulative total and you tax the same payment a second time.
The cross-check is quick: add up the tax amounts of all progress invoices. In the example that is 5,700 + 6,080 + 3,610 = 15,390 euros. Nineteen percent of 81,000 euros of work is exactly 15,390 euros. If the sums do not match, one invoice carries a wrong tax amount.
Run that check after every progress invoice. It takes twenty seconds and it is the only control that finds the error reliably.
Do you have to bill cumulatively?
No, no law prescribes the format.
For contracts for work, § 632a BGB gives you a right to progress payments „equal to the value of the work performed and owed under the contract". The provision calls for a statement that allows a quick and reliable assessment – it says nothing about cumulative or single.
§ 16 paragraph 1 VOB/B governs the same thing for VOB contracts: progress payments are to be granted on request „at the shortest possible intervals or at the agreed dates", in the amount of the documented work including VAT. Again, no format requirement.
So the obligation always comes from the contract. In practice it sits in three places:
- in the payment schedule of a main contractor agreement,
- in the additional contract terms of a public authority,
- or nowhere in writing at all – the client simply returns the invoice with a note saying „cumulative please".
The third case is the most annoying, because it costs you weeks. If you are working for a large client for the first time, settle the format of the progress invoice before the first invoice. One email saves you a rejection and a payment period that then starts over.
The other way round: if nobody asks for the cumulative format, the single progress invoice is usually the simpler route. Our article on the progress invoice shows how that one works. And if you are still unsure whether to issue progress invoices or partial invoices at all: the difference between progress, partial and final invoices has real consequences for your defect liability periods.
Early payment discount: what it applies to
A discount for early payment applies to the amount due on this one invoice, not to the cumulative total.
On progress invoice no. 2 in the example, 2 percent would therefore be 2 percent of 38,080 euros, that is 761.60 euros. Not 2 percent of the top line. Write it out explicitly – „2 % discount on the amount due on this invoice if paid by …" – otherwise the client works it out differently and keeps too much.
Two points on that:
The VAT only changes when the discount is actually taken. You show the full tax on the invoice. If the client pays a reduced amount, the figure the tax is calculated on drops – and you correct the tax amount in the month the payment arrives (§ 17 UStG). Nothing happens before that.
Under VOB contracts a discount only works if it has been expressly agreed. A deduction the client simply makes without an agreement is a shortfall – and you may claim it.
Retention: deduct yes, save tax no
Many construction contracts provide for a retention of 5 to 10 percent that stays with the client until the defect liability period ends. In the cumulative statement it goes right at the bottom, after the VAT:
| Item | Amount |
|---|---|
| Amount due, gross | 38,080.00 € |
| less 5 % retention | – 1,904.00 € |
| payable now | 36,176.00 € |
The retention does not reduce your claim. It is simply paid later. So it changes neither the net amount nor the VAT: you pay over the 6,080 euros even though you have not yet seen 1,904 euros of it.
There is an exception, and it is worth knowing. On 24 October 2013 the Federal Fiscal Court ruled (case no. V R 31/12) that a construction firm may correct the amount as early as the period in which the work was done, if it cannot get at its money for two to five years and cannot release the retention through a bank guarantee either. The tax authorities later adopted this, though with narrow conditions – among other things you must show that a guarantee was not available to you.
Whether that applies in your case belongs on your tax adviser's desk. It is not a box you tick yourself. This article provides general information and does not replace tax advice.
What is left for the final invoice
At the end comes the final invoice for the whole job. In the example: 90,000 euros net.
| Item | Amount |
|---|---|
| Total work (net) | 90,000.00 € |
| plus 19 % VAT | 17,100.00 € |
| Total gross | 107,100.00 € |
| less progress payment no. 1 (gross, incl. 5,700.00 € VAT) | – 35,700.00 € |
| less progress payment no. 2 (gross, incl. 6,080.00 € VAT) | – 38,080.00 € |
| less progress payment no. 3 (gross, incl. 3,610.00 € VAT) | – 22,610.00 € |
| Balance due | 10,710.00 € |
The brackets behind the deductions are not decoration. They are the point:
A statutory duty applies here that does not apply to the progress invoices. § 14 paragraph 5 sentence 2 UStG requires the final invoice to deduct the part payments already received and the VAT contained in them – provided you issued invoices showing that tax. So it is not enough to subtract some figure at the bottom. Anyone reading the invoice must be able to see how much VAT was in the deducted payments.
What gets deducted is the payments actually received, not the invoices issued. If the client cut a progress payment or did not pay it at all, the lower figure goes into the final invoice. That holds across the turn of the year as well.
Our article on the final invoice deducting progress payments shows what that invoice looks like in detail and which wording the tax office expects.
One special case in construction: if you work as a subcontractor for another construction firm, the VAT is often owed not by you but by your client. In that case every invoice on the job shows net amounts with no tax. Our article on reverse charge for construction services explains when that applies.
If you got it wrong
Two cases, two different routes.
You set the completed work too high. That is the harmless case, and it is the real advantage of the cumulative method. You enter the correct figure in the next progress invoice. If it is below the total of the invoices so far, the calculation produces a minus – then you ask for nothing this time and offset it next time. You do not need a credit note for that.
You showed too much VAT. That is the case from the section above, and it does not resolve itself. § 14c paragraph 1 UStG allows a correction, but it requires you to put the invoice right towards your client. It gets harder if the client has already claimed the excess tax back from his own tax office: that claim has to be reversed before you get your money back. In practice: send a corrected invoice, document the process, involve your tax adviser. The earlier, the simpler.
When your money falls due
Under a VOB contract the deadlines are in § 16 VOB/B:
- Progress payments fall due 21 days after the verifiable statement is received.
- The final payment falls due after review and determination, at the latest 30 days after the final invoice is received. An extension to a maximum of 60 days is only effective if it has been expressly agreed and is objectively justified.
Under a BGB contract for work there is no 21-day rule. The progress payment falls due as soon as you have requested it with the statement. Default sets in at the latest 30 days after the invoice is received, unless something else has been agreed.
The trigger matters: the period starts when a verifiable statement arrives. If the client returns the invoice because the measurements are missing or the format is wrong, it starts over. That is exactly why it pays to settle the format up front – in the end the cumulative presentation is less a tax question than a question of how quickly your money arrives.
In office1.cloud progress invoices sit with the job, and the final invoice deducts the payments received together with the VAT they contain. The cumulative statement above that you build through the invoice line items.
And if you are new to working for a main contractor: ask about the payment schedule and the format they want before the first invoice. That is the one minute that can save you three weeks of payment terms. An invoicing software writes invoices with every mandatory detail in minutes.
Handle invoices more easily
Easy Invoice combines quotes, invoices and customer management in the cloud.
Try Easy InvoiceRead next
 Invoicing & Accounting
Receipt lost? How to write an Eigenbeleg in Germany
No booking without a receipt – but there is a substitute. What belongs on a German Eigenbeleg, when the tax office accepts it, and why the VAT is gone anyway.
 Invoicing & Accounting
Pro forma invoice: meaning, template and when you need one
A pro forma invoice demands no money and gives no input VAT deduction. It serves customs and advance information. What belongs on it and where the traps are.
 Invoicing & Accounting
Late payment interest in Germany: rate, formula and example
A customer has not paid for weeks. You may charge interest without asking. Here is how much exactly, from which day it counts and how to work out the amount.